China is still behind where AI advantage is most capital-intensive. In January 2026, Washington tightened export controls again, blocking China-owned overseas data centers from receiving AI chips and shifting H200 licensing to case-by-case review. As of early 2026, Huawei’s Ascend 910C delivered about 60% of Nvidia H100 real-world performance, only 20 to 30% of GB200 Blackwell inference performance, and did so with a 60% larger silicon footprint. On a chip leaderboard, this is not a close call.
Routing Around the Gap
“China did not close the chip gap. It routed around it.”
DATA VISUALIZATION
Frontier Hardware Performance Gap
Yet Huawei’s CloudMatrix 384 could still reach system-level parity with Nvidia’s GB200 NVL72 by wiring together 384 Ascend 910C chips. It also consumed much more power and space. China did not close the chip gap. It routed around it.
That is the central point. China is no longer optimizing for the best component. It is optimizing for usable systems under scarcity. Export controls changed what China had reason to optimize for: domestic inference scale, software compatibility, and deployment viability rather than clean frontier-chip parity.
Domestic substitution is showing up first in deployment. Domestic AI chip shipments reached 820,000 cards in 2024. Market penetration doubled from 15% to 30%. Chinese firms captured roughly 41% of China’s AI accelerator and server market in 2025. As of early 2026, Ascend 910C reportedly powered more than half of Chinese domestic data centers, even as adoption remained supply-constrained. The result is growing operational sufficiency, not parity.
The Toolchain Bet
“The strategic object is not just the model. It is the toolchain.”
DATA VISUALIZATION
Chinese Open-Weight Model Releases
Software is what makes that sufficiency usable. Chinese open-weight model releases rose from 32 in 2022 to 337 in 2025. By the end of 2025, Qwen had more than 100,000 derivative models on Hugging Face. Open diffusion lowers the hardware bar. More of the stack can run on good-enough domestic inference hardware without waiting for frontier chips. The strategic object is not just the model. It is the toolchain.
That reframes the role of China’s major AI firms. They may not be competing mainly to produce the single best model. Qwen’s derivative sprawl suggests platform reach. ByteDance’s Doubao matters for different reasons: consumer scale, very large enterprise token usage, and roughly 160 billion yuan of 2026 AI capex, which makes it a hyperscale inference and distribution platform as much as a model vendor. Model release, cloud distribution, and enterprise demand increasingly reinforce one another.
This equilibrium is strategically useful and commercially awkward. Broader diffusion makes weaker hardware more valuable. It does not guarantee attractive margins.
The State as Resource Router
INTERACTIVE ANALYSIS
State Capital Routing Across the Stack
State capital prioritizes foundational infrastructure, chip R&D, packaging, and storage to keep the domestic stack viable under export pressure.
The state sits in the middle of this as a resource router. China’s 2026 Government Work Report allocates 755 billion yuan in central budget investment and 800 billion yuan in ultra-long special treasury bonds for major national strategies and security-capacity projects. Big Fund III adds another 344 billion yuan, with 70% allocated to foundational infrastructure and chip R&D and 30% to advanced packaging and AI storage. In December 2025, MIIT approved Huawei and Cambricon AI processors for government procurement. Its deep-synthesis metadata and watermark protocols had already taken effect in September 2025. These are tools for shaping a market.
The operating-system scheduler metaphor still works. The state can allocate cycles and route demand. It cannot guarantee efficient execution. The same evidence that supports strong mobilization also supports a narrower conclusion on use: China appears strongest at moving money, approvals, and provincial implementation, and weaker at ensuring equivalent utilization downstream. Mobilization and utilization are not the same thing.
Deployment Breadth as Power
“China may matter in AI because it can embed AI broadly across an economy, not because it owns every frontier benchmark.”
The ambition is broader than semiconductor substitution. Official AI+ framing stretches across manufacturing, healthcare, logistics, robotics, scientific innovation, culture, livelihoods, and governance. AI is being treated less as a software sector than as infrastructure for the rest of the economy. The open question is whether deployment outruns actual use.
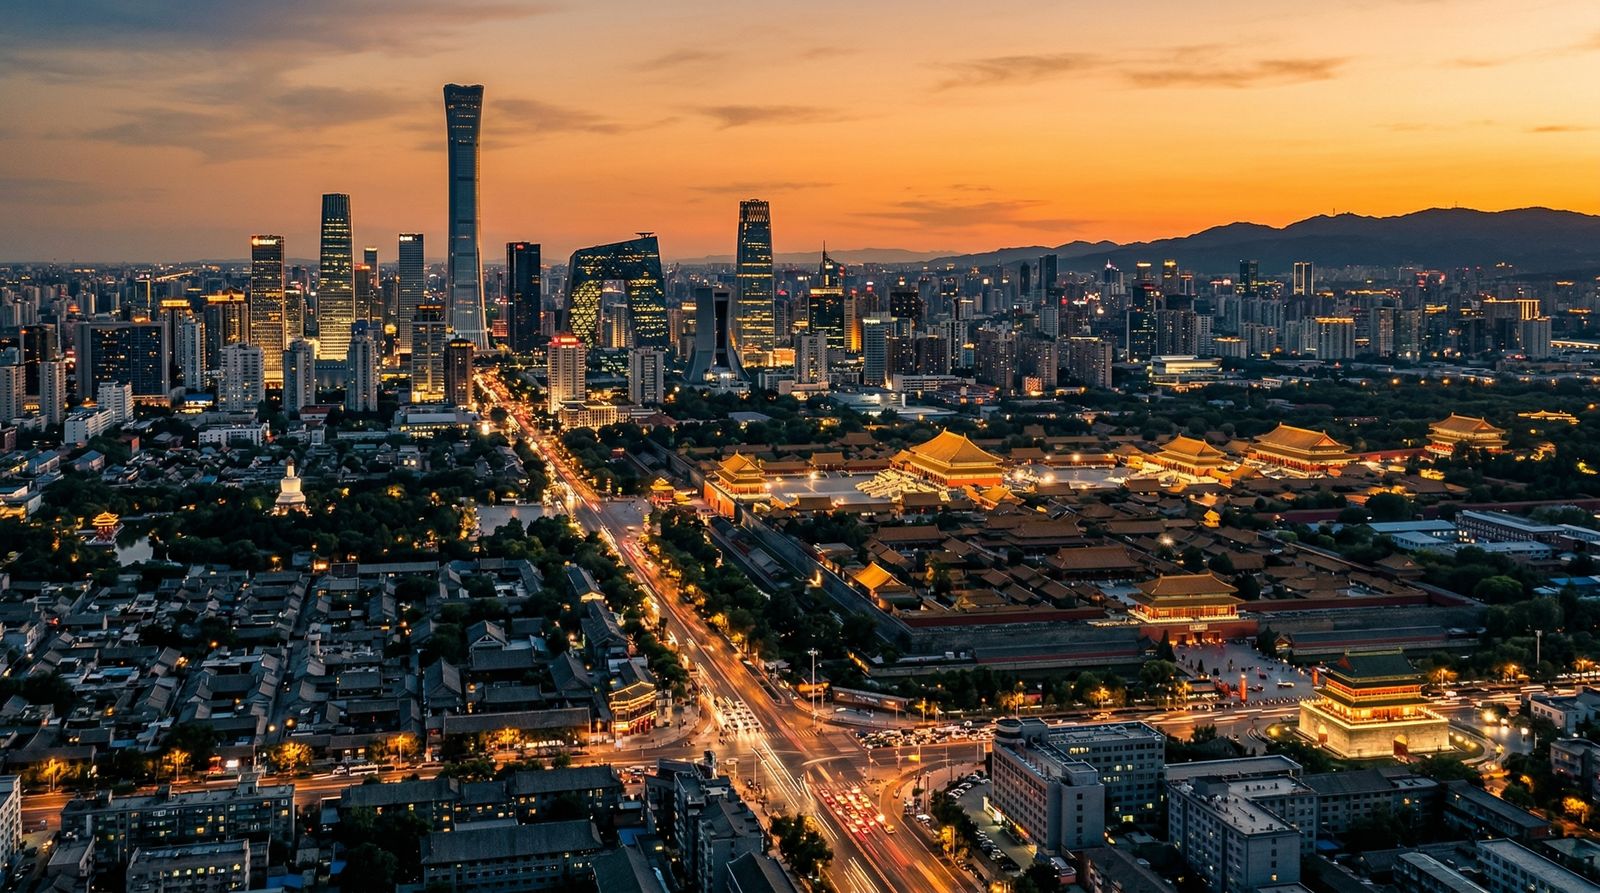
China’s geography suggests a system, not a single champion. Shanghai combines large-model concentration with intelligent-terminal scaling and smart-factory deployment. Shenzhen has a Huawei-based 10,000-card cluster, and local robotics firms are already generating meaningful embodied-intelligence revenue. Hangzhou adds data-labeling capacity and scenario-competition mechanisms for robotics, autonomous driving, and industrial use cases.
China increasingly looks like a circuit board. Shanghai and the Yangtze River Delta specialize in large models, embodied intelligence, and systems integration between frontier models and industrial modernization. Shenzhen and the Greater Bay Area function more as a compute-substitution and industrial deployment zone, especially where domestic chips can be tied to manufacturing and hardware ecosystems. Hangzhou strengthens the commercialization and scenario layer that moves models into usable settings. This is less a leaderboard than a division of labor.
That does not remove friction. Regional specialization can also mean duplication, siloing, and coordination drag. Still, the Chinese AI project is better understood as distributed systems integration than as one national champion standing in for the whole effort.
Capability Spread Under Constraint
Part of what this buys is substrate. In February 2026, UNESCO and the Chinese Academy of Sciences launched remote access and training on the ScienceOne AI platform, widening institutional access to AI-for-science infrastructure. BAAI released FlagData and FlagOS 2.0 with support for more than 20 mainstream AI chips, lowering software friction across heterogeneous hardware. In March 2026, Tsinghua launched six AI-themed courses for Asian Universities Alliance members, and U.S. reporting says Tsinghua-led embodied-AI research is feeding spinouts. At NeurIPS 2025, China-based lead authors outnumbered U.S.-based and Europe-based leads for the first time. Shared tools, training, access, and transfer mechanisms help capability keep spreading even when top-end hardware is constrained.
The strategic payoff is broader deployment. AI+ policy treats AI as a way to upgrade traditional industries. Shanghai explicitly links models, terminals, and smart-factory rollout. Shenzhen combines domestic-compute substitution with industrial ecosystems in manufacturing and hardware. China may matter in AI because it can embed AI broadly across an economy, not because it owns every frontier benchmark. Deployment breadth is a kind of power.
A Broad Market, Not a Pretty One
DATA VISUALIZATION
Reach vs Revenue in China's AI Market
But it is not a pretty market. In the 2025 to early-2026 snapshot reflected in the brief, Chinese flagship models including DeepSeek, Qwen, and ChatGLM were priced roughly 10 to 20 times below comparable U.S. offerings. Chinese AI apps commanded 46% of global monthly active users but generated only 1.23% of top-100 AI revenue, and the domestic LLM market remained under $1 billion. Low prices buy reach by selling away margins.
That separation is the main analytical discipline here. China has not solved the frontier chip problem. The hardware gap is real. Export-control pressure is real. The workaround architectures still carry ugly penalties in power, space, and efficiency. But China is turning chip scarcity into a systems problem rather than a stopping condition.
So what counts as winning if benchmark leadership and deployment power diverge?
Probably not one clean thing. China is not recreating the U.S. frontier stack chip for chip. It is building a lower-cost national AI operating layer that is messy, constrained, and far from elegant, yet increasingly hard to ignore. That layer may never deliver frontier monopoly, clean utilization, or attractive margins. It may still deliver enough: enough distributed capability, in enough sectors, across enough institutions, that chip inferiority functions as a throttle rather than a stop sign.